
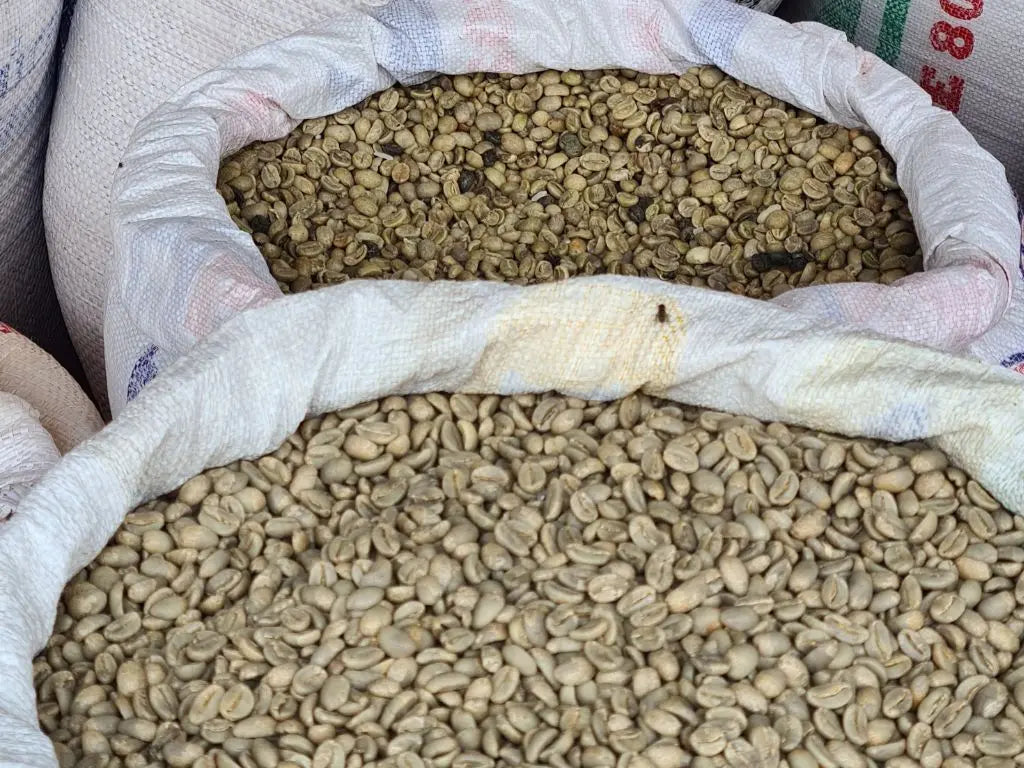

Most coffee roasteries do not disclose where their raw coffees come from. Instead, communication is dominated by brand names or emotions. The fact is: almost all roasteries buy and roast the same raw coffees as everyone else does. We give you tips on how you can still guess what you're drinking.
When we conducted our second tasting of Italian espresso, we noticed that hardly any roastery declared the origin of the coffees they used. Instead, there was talk of "balanced blends" and "carefully selected" raw coffees.
And this is not an isolated case.
This applies to many coffees that are drunk daily in Germany, Switzerland, and throughout Europe. So if no information about origin is provided – what are we actually drinking?
Many skip transparent origin labeling. No country, no region, no farm, no processing method. Why exactly?
Why origin is not stated
There are several reasons why roasteries omit origin information.
Flexibility in blending:
The components of a blend can be adjusted depending on market availability and price fluctuations. This substitution is common practice. As long as the coffee tastes the same, coffees are swapped out. Especially in times like now, when prices have risen sharply, blends are remixed to compensate for price increases.
Sensorily there must be no deviation, but in terms of content, especially the constantly available blends look different again and again. A classic example is the substitution between washed coffees from Honduras and Peru: in both countries, coffee is washed-processed for large volumes. The general character of both coffees is similar, with nutty and citric notes to the fore.
These coffees are often described as "cheap acidity components" - at least before November 2024, before prices rose sharply. Additionally, Honduras is on the northern hemisphere and Peru on the southern hemisphere, so harvest times are staggered. Ideally, there is always fresh coffee from these countries, which makes substitution even easier, but above all increases procurement flexibility.
Branding takes center stage – not the contents
We are repeatedly amazed by a brand self-image that apparently trumps transparency. There are indeed roasteries that specify a blend ratio based on the species used, almost always Arabica and Robusta.
We then read, for example, "100% Arabica" - if we used only this information for wine, it would be as precise as: 100% wine from red grapes. We can do better than that.
But we find this description even more superficial: coffee with "the best beans from the best growing regions in the world". This is not only very simplified marketing speak, above all it is remarkably anachronistic in 2025 and leaves consumers in the dark.
No accountability to consumers
Neither Switzerland nor the EU requires the exact origin (country, region) or variety, cultivar, or processing to be stated on the coffee package, as long as no misleading information is provided.
However, if origin is stated voluntarily, it must be correct. It is permissible to name a broader geographic area (such as "South America") instead of a country. The statement "100% Arabica" is allowed if it is true.
Transparency is voluntary, but when stated, it must be correct and not misleading. The EUDR deforestation regulation that takes effect in 2026 does require transparency, but only between the entity placing goods on the market and EU authorities.
The regulation requires importers and traders to be able to prove the exact origin (down to the plantation) to exclude deforestation. However, this information does not necessarily have to appear on packaging for end consumers, and will probably not be handled this way by any roastery.
What we can still know
Even if nothing is stated on the package, contextual knowledge, sensory analysis, and two solid sources help clarify the picture: The 2024 Coffee Report by Brand Eins and Tchibo shows which countries export the most coffee. And the European Coffee Report 2023/24 proves:
Over 58% of coffee imported into Europe comes from just two countries: Brazil and Vietnam.
This is hardly surprising because Brazil and Vietnam are the world's largest coffee producing countries. Brazil produced 66.4 million 60kg bags of coffee, Vietnam 30.1 million. Or to put it another way: Brazil produced 38% and Vietnam 17% of global coffee supply. This is followed by Colombia with 7% and Indonesia with 6% (see statistics).
Coffees from Brazil and Vietnam are therefore used almost universally in most coffee products. It should be noted that Vietnam exports almost exclusively Robustas, and Brazil is the largest Arabica producer but the second-largest Robusta (Conilon) producer.
Looking at the statistics in the European Coffee Report, we can read a great deal.

Germany imported the most coffee of the 27 EU states; from 2021-2023 it accounted for almost 34% of all imports into the EU. Some of the largest roasteries like Tchibo, Dallmayr and co. are located in Germany and purchase coffee. Italy is the second-largest importer and purchased 23.5% of all raw coffees into the EU during the same period. This is followed by Belgium, Spain, and the Netherlands.
The largest importers in the EU
Germany, Italy, Belgium, Spain, and the Netherlands accounted for more than 82% of total raw coffee imports into Europe in 2023. The largest roasteries in the mentioned countries are:
- Germany: Tchibo, Jacobs Douwe Egberts
- Italy: Lavazza, Illycaffè
- Belgium: Miko Coffee
- Spain: Cafés Candelas
- Holland: Douwe Egberts
Savings on raw coffee - a "race to the bottom"
This graph is particularly interesting, as it reveals much about the competitive pressure between coffee roasteries. From 2021-23 we see a sharp decline in imports of Brazilian coffee and a sharp increase in coffee from Vietnam on the other hand.

What does this mean?
Since a large majority of Arabica coffees from Brazil are imported into the EU, these were apparently replaced with Robusta from Vietnam. And because the latter became increasingly cheaper over the same period, it's clear that here not only was the sensory aspect adjusted, but above all the costs.
But today it looks different: Robusta has become more expensive and is now twice as expensive as Arabica from Brazil in 2023. Compared to this, Robusta is still cheaper today.
If nothing is stated on the packaging, the probability is very high that the roasted coffee comes to a large extent from Brazil and Vietnam.
Uganda ranks third with 7.8% among the most imported coffee origins.
Over 70% Robusta is produced and exported in Uganda - so here too it is likely that it is for price reasons that Uganda is so important for the EU market. On the other hand, we see far more bio-certified cooperatives in Uganda. Therefore: bio-certified Robusta in Germany comes largely from Uganda.
Mass-market vs. specialty
The import data also shows: countries like Ethiopia, Guatemala, Mexico, or Costa Rica also export to the EU. However, in significantly smaller quantities, and often for the specialty market.
What makes coffee from these countries special?
Ethiopia
- is famous for floral and fruity coffees. In Ethiopia, coffees are divided by Grades, with Grade 1 coffees representing the highest quality
- for the mass market, Grade 3 and Grade 4 coffees are often used, which are less uniform and clean, but still retain the original taste characteristics
- often just a few percent in a blend is enough for the coffee to smell different in aroma and thus stand out from the crowd
Peru, Honduras, Mexico
- are among the leading exporters of dual-certified (organic and fair trade) coffee. These are typically washed, citric coffees, and are often substituted
But: what about Colombia, as the third-largest coffee producer?
Switzerland in comparison
The chart from the Swiss Sustainable Coffee Platform shows: in Switzerland too, most coffee comes from Brazil, but the structure is significantly more diverse. And: much less Robusta is imported.

Colombia ranks second. We suspect that Nespresso, one of the world's top three roasteries, is responsible for this. Since Nespresso's introduction in 1986, according to our own research, 120-150 capsule varieties have been filled with coffees from Colombia.
Coffee from Colombia is very diverse, can be floral, fruity, chocolatey, light and heavy, and offers great variety in applications, especially for a diverse assortment.
Vietnam ranks third, but is closely followed by India with 7%. Here we suspect that mainly washed Robusta is imported, which compared to the dry-processed Robusta from Vietnam is usually softer.
Costa Rica and Guatemala also appear earlier. These are coffees that are not only more expensive, but also bring a special story for many roasteries.
Especially Costa Rica is also a popular travel destination for Swiss tourists - it's quite possible that here imagination, wanderlust, and consumer behavior meet.
Why origin labeling matters
In very few cases, and this is consistent across all European countries, is the exact origin communicated. We increasingly see a "regional" limitation, for example: coffees from Central and South America.
With wine, no one would accept a label that simply says "from Europe".
With coffee, that seems to be acceptable.
But precisely through this, roasteries evade transparent communication, because:
- No origin = no accountability
- No story = no connection
- No transparency = no control
Whoever does not say where the coffee comes from leaves themselves open to swapping at any time – without firm commitment to transparency or long-term partnerships. Yet this is precisely where great opportunities lie: those who tell the individual stories can reach an even broader audience.
Tips on how you can guess the contents
If nothing is stated on the package, we still roughly know what's in it.
Not in detail, but in pattern:
Dark-roasted coffees marketed as "strong":
- often coffees from Brazil and Vietnam – efficiently produced, inexpensively sourced, interchangeable at will.
- the coffees have little acidity, offer a nutty flavor profile, and the Robusta provides the classic espresso note
Milder coffees
- often with washed coffees from Peru or Honduras, because they are on the one hand sensorially substitutable, cheaper, and bring a citric acidity that is especially attractive for longer coffees
Organic and fair trade coffees
- often from Peru, Honduras, Mexico, Tanzania, and Uganda
- that's where the largest dual-certified coffee cooperatives are located
If we know this, we can make more conscious choices. And perhaps buy the next coffee from a place where origin is more than an empty promise.
Annex: Legal situation
Legal situation in Switzerland:
- There is no general obligation to state the exact origin of coffee beans (e.g., country, region) on the packaging. The statement "100% Arabica" is permissible as long as it is correct and actually contains only Arabica beans
- However, if an origin is declared (e.g., "from Peru" or "from South America"), this information must be correct and not misleading. False or deceptive statements are prohibited and are monitored
- Swiss origin designations ("Swiss coffee") may only be used if the beans have been fully processed in Switzerland. The origin of the beans themselves does not have to be stated, as long as no misleading Switzerland association is created
- For processed food products (such as roasted coffee), it is permissible to state a broader geographic area (e.g., "South America") instead of a country, provided this corresponds to the facts
- The variety (e.g., Arabica, Robusta) does not have to be stated, unless it is advertised ("100% Arabica"), in which case it must be correct.
Legal situation in the EU
- In the EU too, there is no general obligation to declare the exact origin of coffee beans on the packaging. Statements such as "100% Arabica" are permissible as long as they are correct
- If an origin is voluntarily stated, it must be truthful and not misleading
- Since 2020, the origin of the "primary ingredient" must be declared if it does not match the stated origin of the product. Example: if a coffee is sold as "Made in Germany" but the beans come from Brazil, the origin of the beans must be stated. For pure coffee without such claims, this obligation does not apply.
- The new EU deforestation regulation (EUDR) requires importers and traders to be able to prove the exact origin (down to the plantation) to exclude deforestation. However, this information does not necessarily have to appear on packaging for end consumers
Sources:
- Noerr: Special origin designations for protected designations of origin
- Gastrosuisse: Declaration
- LW-RK: Correctly state origin on packaging
- Focus-Swiss: Swissness for SMEs
- BMEL: Obligation to indicate origin for pork, sheep, goat and poultry meat
- CMS-Deutschland: National special obligations in origin marking
- Delikatessen-Schweiz: The secret of perfect café crème
- BLV: Explanations on the EDI regulation concerning the
- Information about food (LIV)
- BMEL: EU-wide uniform food labeling
- Official Journal of the European Union: REGULATION (EU) No 1169/2011 OF THE EUROPEAN PARLIAMENT AND OF THE COUNCIL
- WKO: Food Information Regulation (LMIV)
- KVG: FAQ on the application of Regulation (EU) No 1169/2011 concerning the information of consumers about food - LMIV