

Since 2020, we have published our green coffee prices on our website. Numbers alone tell little, however. That's why we're presenting them together with the context behind them for the first time in our first Transparency Report 25/26: how we buy, what exchange prices do to our partners, and what stories lie behind three of our coffees.
This article reproduces the complete Transparency Report 25/26. If you prefer to read the designed version with all images in one go, you can download it here: Transparency Report 2025/26 (PDF).
Context, not just numbers
We're a transparent company and communicate a lot through our various channels. We've previously delivered context for our prices separately from the numbers – on our website, on YouTube, and on social media. We've reported what we do, but also what we don't do. Now we're bringing context and numbers together for the first time.
In just over eight years as a roastery, with a broad product range and direct relationships with coffee producers, we've learned a lot – and continue to learn. Through our own experience running a coffee farm, coffee trips, and countless conversations with producers, roasters, and traders, numbers take on meaning. Without context, they say little, and that's always a shortcoming when looking purely at the FOB price. Behind every number are stories. We're telling three of them here: Farmers Coffee (Brazil), Yulma Argueta (Guatemala), and BridAzul (Nicaragua).
Coffee is a people's business
When a coffee producer told me in Kenya in 2013, "Coffee is a people's business," I already believed him. But I could never have imagined that today, working with coffee, I'd be dealing much more with people than with the coffee itself.
Since 2017, we've been roasting commercially. Back then, we set up a roastery in the basement of a residential building, bought coffee from friendly traders, and simply got started. Our product range was modest, yet we aimed to know everything about the coffees we purchased. We sought contact with importers who could tell us more about the background. We wanted to understand what the FOB price was, and especially what it meant – and what it didn't.
As a young company – since January 2017 as an independent GmbH – we had to develop a strategy: be simultaneously economically successful in the long term, stay close to producers, and pay correct prices for green coffee. Because good coffee is the result of good relationships. For the majority of our coffees, it started with a meeting with a producer. Conversations developed from that meeting, and when it clicked, green coffee samples followed. If we liked those, an initial import would follow. And from an initial import came joint projects – always in a way that worked for both sides.
This report is a testimony to its time. When we publish it again in a year, I hope many of the names mentioned here will appear again. We dedicate a substantial portion of our time to relationship maintenance. We work with coffee, but we're even more in the people's business.
— Philipp Schallberger, on behalf of the sourcing and roastery team. Basel, June 2026.
Thinking long-term in short-term times
The past five years have been extremely eventful in terms of green coffee. The pandemic, supply shortages, the coffee exchange at all-time highs, and growing challenges for coffee farms due to climate change have required all participants in the coffee chain to remain highly agile.

Photo: Tatiana Gomez
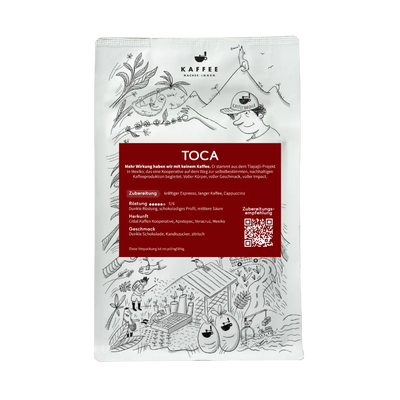
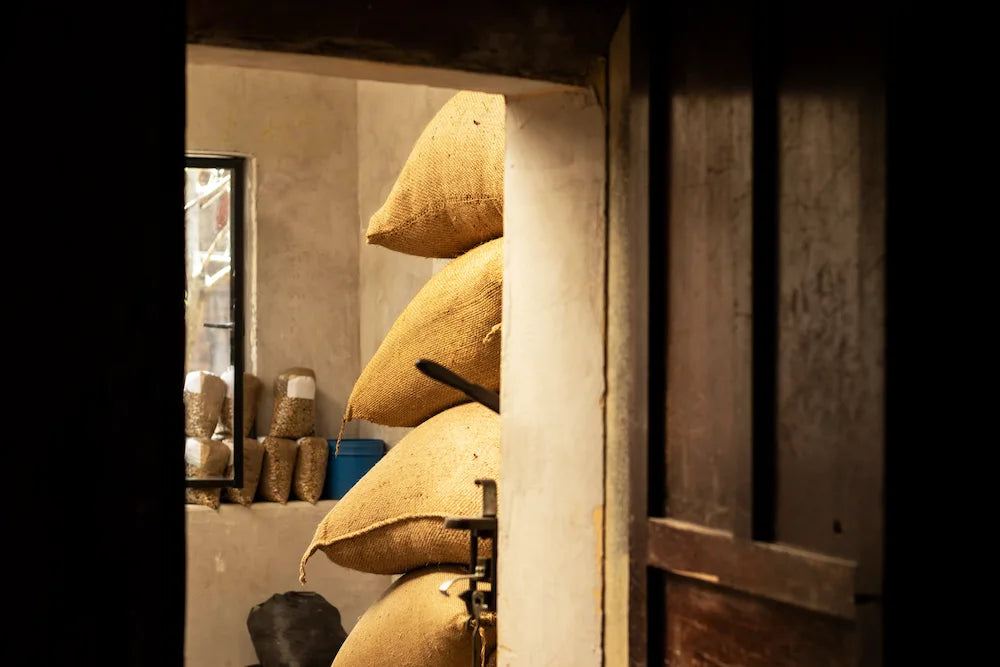
In the Sierra de Zongolica in Mexico, we've been working with Ensambles on the Toca project since 2021. The young cooperative Citlal Kaffen stores its coffee in parchment in an old processing plant that was closed in 2013. Now they've put it back into operation. This facility was once a chicken farm – and also a church for the surrounding communities.
How we think about our role as a roastery
We exchange information with our production partners daily. They're far away, but they're the ones who make it possible for all of us to drink coffee. With them, we learn what it takes today so we can still drink coffee tomorrow. Three formats show how we think about our work:
From Source to Sip – the roasting film
In our roasting film, we take you on a journey from the coffee's origin to our roastery in Basel. We show what goes into every cup of coffee, starting where the coffee comes from. Because without coffee producers, there are no coffee roasteries. A film by Larissa Bürgi about the people and stories behind the coffee.
Our 10 Coffee Commandments
Pointed and ambitious: In our 10 Coffee Commandments, you'll find ten compelling statements that sum up our work as a coffee roastery.
APAS and the Brazil coffee trip 2026
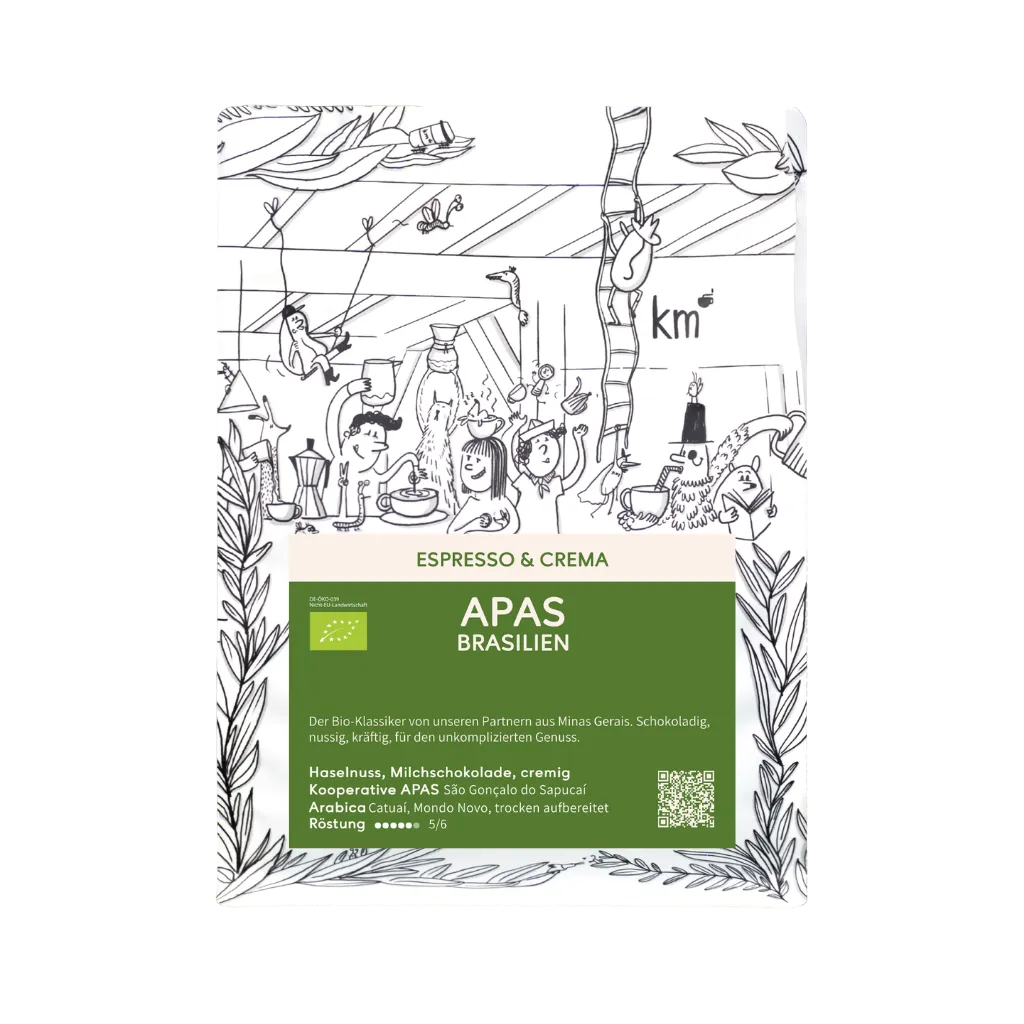
The APAS film is a tribute to the APAS cooperative and the relationship we've been building for several years. On the Brazil coffee trip 2026, Benjamin, Philipp, Gabi, and Larissa drove 1500 km through Minas Gerais and Espírito Santo: to bioproducer Marcia, to the cooperative export lab Copervass, to the APAS cooperative, and to Farmers Coffee. What comes out is a different picture of Brazil than the one that usually sticks in people's minds – and conversations about partnership that you can't have via WhatsApp.

Visiting the Brioschi family in Pedra Azul, Espírito Santo.
What we purchased in 2025/2026
The coffee harvest year differs from the calendar year because harvests occur at different times depending on the world region. We've chosen June through May as our reporting period because we also make many contracts in the first half of the year.
Complete purchasing data can be found in the PDF
| Metric | Value 2025/26 |
|---|---|
| Share of partnerships 3+ years | 37 % |
| Ø SCA quality score | 85.8 |
| Origin trips 2025/26 | Ethiopia, Brazil, Mexico, India |
| Number of producers/cooperatives | 43 |
| Countries of origin | 16 |
| Contracted green coffee | 129,110 kg |
| Ø FOB price (USD/lb), unweighted | 5.76 USD |
| Ø FOB price (USD/lb), weighted | 4.81 USD |
| Ø relationship duration | 4.52 years* |
* We explicitly do not count coffees from our Adventure line here. These coffees are often one-time purchases and are primarily aimed at excellent quality in the cup.

In the mountainous region around Villa Rica, César Marin produces specialty coffee with his family on a farm that operates without external inputs. They produce all fertilizers and plant protection products themselves using regenerative practices. This makes them immune to fluctuations in the fertilizer market. What they're not immune to – and it's not a farm – is producers' exposure to coffee price fluctuations. Even though we keep bringing up the topic of fixed prices, we haven't been able to establish any yet. A fixed price could help cushion these fluctuations.
The green coffee prices from 2025 to 2026
In early January 2025, the C price – the global futures reference price for Arabica on the New York ICE exchange – was around 330 US cents per pound of green coffee. On February 12, 2025, Arabica reached its absolute all-time high: over 442 cents per pound, more than five times the long-term historical average. The previous record high was from 1977.
| Time | C price (US cents/lb) | Classification |
|---|---|---|
| Early January 2025 | ~ 330 | already significantly elevated |
| February 12, 2025 | > 442 | absolute all-time high |
| Early June 2026 | ~ 250 | nearly halved from the peak |
Three causes behind the historic price increase
In summer 2025, the price first stagnated and then fell slowly. US tariffs caused uncertainty on all sides. This led to short-term, sharp fluctuations – and especially to producers waiting before selling coffee at all. Gradually, speculative capital withdrew, and prices fell in fall 2025.
Spring 2026 brought the turning point. Brazil's 2026/27 harvest is likely developing into the largest harvest ever measured, with an estimated 66.7 million bags – 18 percent more than 2025. Exchanges react quickly to news, and so the positive reports from Brazil immediately affected the price: in early June 2026, the C price fell to around 250 US cents, nearly half the high from 15 months earlier.

Heading uphill in the Sierra de Zongolica, Mexico
What do these fluctuations mean for us?
We move with prices in an overall movement, up and down – at least for producers who use the C price as a reference. On top of the C price comes a differential, an individually structured premium. Some producers set the price for us, others ask us what we're willing to pay. It's a mix of approaches.
All producers know the movements on the New York exchange very well, as this influences their respective national coffee price. What happens in New York affects the national price in Mexico, from which regional prices in Chiapas, Veracruz, or Puebla are then set. Prices emerge from regional prices, mixed with quality premiums, ecosystem services, and a perceived markup. A price discount for us occurs where we've purchased long-term.
What do these fluctuations mean for producers?
The C price swung between 270 and 440 US cents per pound over the past 18 months. For producers, that means: sell or wait? Those who fix prices too early leave money on the table; those who wait too long risk a crash. Producers have also realized how speculation works and can influence prices by holding back their coffee.
Especially Brazilian farmers were reluctant to sell in early June 2026, even though the harvest was underway. That's because every investment decision – new plants, fertilizer, labor – requires planning security that simply doesn't exist right now. The Iran war and inflation are causing additional costs for fertilizer and logistics, so decisions among our partners are also being made hesitantly.
Coffee producers have gotten used to fluctuations because the vast majority tie their prices more or less to the exchange. But this recent scale of fluctuations has created a lot of uncertainty. So producers in Brazil, Mexico, India, and Indonesia sold more coffee to the domestic market than they exported. Local sales generate quick cash, while exports and payment take several weeks.
Three stories behind the numbers
Farmers Coffee and the Compadre (Brazil)
In 2023, Philipp visited Farmers Coffee in Venda Nova do Imigrante on a recommendation from algrano. "They have drive," he was told. Farmers Coffee is called that because all four founders are sons of coffee producers. At their first meeting, they had just begun buying coffee from producers in Espírito Santo and marketing it. Their education at the renowned IFES university, their openness, and their youthful drive helped them grow quickly.

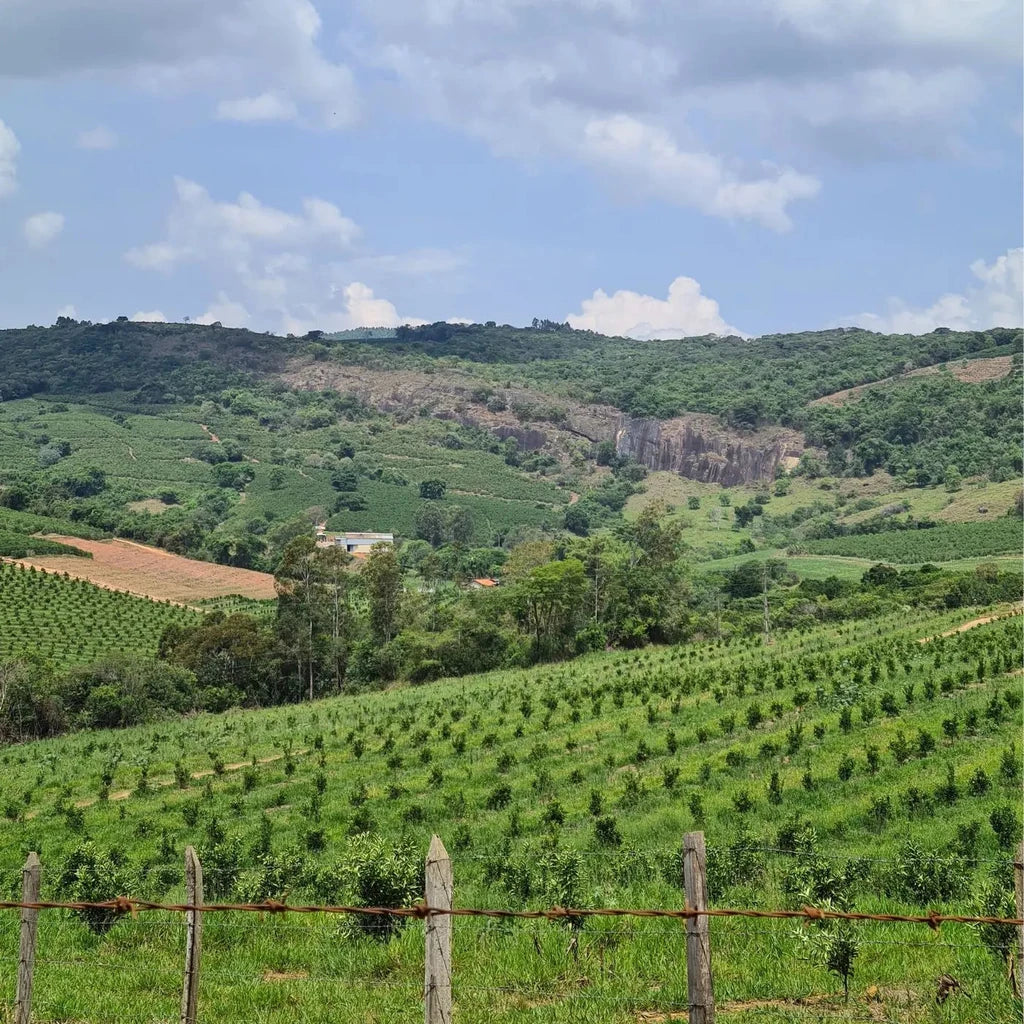
The Romão family supplies the Arabica component in the Compadre.
In 2024, they visited us in Switzerland, and we discussed how we could work together. That's how the idea for the Compadre Espresso came about. Because they buy from and export Arabica and Conilon robusta producers, they could assemble the blend according to our idea: a 50:50 blend, which Farmers Coffee mixes for us before export and fills into coffee bags as a pre-blend. They established a new process for this and fully committed to the project. The coffee has found favor, and in 2026 we visited them again in a small group – as well as the family who supplies the Arabica component in the Compadre.
Farmers Coffee is extremely customer-focused and sees roasteries as partners they want to understand. We share all numbers, inform each other about projects and business performance – the trust is there. Partners like Farmers Coffee show how much fun it is to work with strong, networked companies who are themselves close to producers.
Yulma Argueta and the Amigo (Guatemala)
Yulma Argueta had to turn 40 before she started coffee production. Coffee producers are typically born into a coffee family and eventually take over the operation. Yulma's story was different. With her family, she ran a farm in Baja Verapaz, Guatemala, that focused on horse breeding and timber production. But coffee was always her passion, so she started planting a few hectares relatively late in life. She sold her first harvests on the local market – she wasn't really aware of her coffee's quality.

Yulma with Nadja and Philipp at the World of Coffee in Geneva, 2025
She came into contact with Grounds for Empowerment, an online program that created a network of Latin American female producers during the pandemic. Philipp gave a workshop on storytelling at the time, and Yulma participated. She shared her biographical story with the group. It was an emotional moment that created a connection. We stayed in touch, and a year later she sent us samples. The washed coffee from 1800 m above sea level was very good, but we couldn't find an export partner willing to take on the work for just a few bags of green coffee.
It worked out in 2025: Yulma was able to export coffee outside Guatemala for the first time. We roasted her coffee for the Amigo filter coffee. It went over well with other roasteries too, and that's how we could help her expand her network. So her coffee can be exported with as little effort as possible, we networked her with various exporters; she decided on algrano. In 2026, we purchased from her for the second time. We see it as our responsibility to continue networking partners so they can diversify. Because that's how we grow together.
BridAzul and the Doña Margarita (Nicaragua)
When we took over Finca Santa Rita in Nicaragua in 2017, BridAzul's team was just beginning various fermentation experiments. They tested hundreds of processes and stabilized them until they had their handful – with which they still regularly make it into the top 10 at Cup of Excellence competitions. In one of these processes, cherries are sorted in a water channel, placed in rain barrels, closed, and fermented for four days. After that, they dry in the shade. The hours in the barrel and the duration of drying produce different sensory profiles.

One of them, BridAzul named "Lucid Dreams" – a coffee that was a dream, whose flavor notes were so clear to see. Each year it shows notes of sour cherry and passion fruit, is both heavy and juicy. We were delighted and wanted to name the coffee after a person, as we do with all our coffees. Since our partner on-site didn't want to appear on the package, we named it after a former owner of our Finca Santa Rita: Doña Margarita. The name resonated, and so did the coffee.
Each year, BridAzul refined the process and limited the cherries used to two farms – Santa Rita and a neighboring farm – making the coffee increasingly consistent. Today we serve it in our cafés for three months. There are regular customers who wait a long time for this season and otherwise ask: "When's Doña back?" When a coffee gets a nickname, it's on its way to becoming a classic.
How we buy coffee
"Start with the end in mind" is our motto before we even think about a specific green coffee. First, we ask ourselves: What purpose should the green coffee serve? What drink, extraction method, customer group, flavor profile, and price expectation? Once these questions are clarified, we first look within our existing network of producers. Ideally, we buy different coffees from the same producers.
Diversification of origin
In recent years, we've broadened our portfolio geographically and structurally. We long had a large Brazil share in our portfolio and still do, but we're diversifying within Brazil across different regions (Minas Gerais, Campo das Vertentes, Matas de Minas, Espírito Santo). Indian coffees are newer to our range, and the share of Colombian coffees – measured against Colombia's global importance – is still very low. Through this diversification, we're preparing ourselves for possible supply disruptions. Especially with larger volumes, we've become more risk-averse and stock up on regularly roasted coffees, because some surprise is always waiting.

Sorted and packaged coffee is loaded into containers in Nicaragua.
Diversification of importers
We typically buy through carefully selected importers with whom we share much in terms of values. We've been working with algrano since 2017 and source the majority of our coffees through the platform. In Mexico we work with Ensambles, This Side Up gave us access to coffee from India. We have a long-standing friendship with Falcon, with Plot Coffee we traveled to Ethiopia where they're well-networked. We rely on Belco in Colombia. Especially for micro and nano lots, we work with specialized importers who have a clear specialty. So we've greatly broadened our importer network.
Order as early as possible
We try to give our partners a volume estimate six to eight months before the coffee arrives so they can plan. The early order is followed by a contract, which we also sign as early as possible. Regularity and predictability lead to necessary stability and security on both sides.
Pricing
Pricing is as individual as the coffees themselves. Broadly, there are three approaches:
We prefer it most when producers state their price and explain it clearly. Very low prices make us suspicious, as do fabulous prices that no longer reflect production costs but rather brand value. To get as close as possible to a "right" price, it takes open conversation – so that both sides can say the price was fair. Negotiating prices is part of our work, as is avoiding speculative practices.
Contact and visits
We've visited all the producers of the green coffees we purchase most – from one-time visits to regular ones. Throughout the year we're in regular contact, sometimes more superficial, sometimes deeper, as in any partnership. Not every delivery runs perfectly: delays happen, sometimes damaged coffee bags, rarely also cancellations because, for example, a community lot can't be mixed. In the coffee industry there's always some challenge somewhere. But we've learned that there's always a solution. And when we find it together with the producers, we're building the foundation of a strong, sustainable relationship.

Year after year we visit the Toca project, strengthening our trust.
Time differences, calls, and trips
A romantic long-distance relationship works when there's regular communication. A partnership long-distance relationship follows the same principles. WhatsApp seems to be the favorite tool of coffee producers; we write emails when it's about concrete contracts. You have to imagine: we sometimes discuss six-figure amounts, agree on volumes and prices via WhatsApp – and finally there's still an email tying up all the loose ends of the chats.
Since we source most of our coffees from Central and South America, we communicate with Yulma, César, and company when late afternoon arrives here. One of our running jokes: "The Latinos are awake now, time for chatting!" It's important that we're in touch not just before and during the harvest, but especially afterward – between harvests. This in-between time is our strategic communication time: the pressure is off, we can recap and look toward the future together. Communication during harvest is like a 90-minute soccer match: focused and fast. Between harvests it's like training – more time, more space. That's why we typically schedule our trips during the season between harvests.
Trust before control
Much in our daily work as an SME happens through direct communication, personal exchange, and trust given. Less happens through certifications and formal control – internally and externally. On one hand, because we know our partners directly, exchange with them, and visit them; on the other, because they themselves forego certifications and we as buyers don't necessarily require them. Trust before control is our approach. It requires exchange – and closeness.
The closeness framework by Edelmann et al. (2020) distinguishes four types of closeness:
In organizational, social, and cognitive closeness, we're tightly calibrated with many partners; institutional closeness remains informal in nature. To secure ourselves externally here, third-party certifications (Fairtrade, EU/CH-Bio, Demeter) would help. But we won't be leading all partners to such certification for the foreseeable future. If they wish it, we support them – as we did with APAS and are currently doing with Toca.
We also systematically evaluate what role producers' own guidelines can play for us. Participatory Guarantee Systems (PGS) are local, alternative quality assurance systems. They certify producers through active participation of all stakeholders and are based on physical, social networks, direct exchange, and trust – a bottom-up approach that can adapt to the specific ecological and social conditions of a region. When we buy coffees without knowing exactly the background, they're at least certified coffees – like a bio-certified robusta lot via InterAmerican. We don't sell coffee in classical retail and therefore aren't bound by third-party certifications that are often required in food retail.
How we understand sustainability as a company is in Sustainability at the coffee makers. We disclose our measured CO₂ footprint of the roastery in Our CO₂ footprint, and how many emissions are created in cultivation is shown in the analysis Environmental impact of coffee cultivation using the example of our Finca Santa Rita. We explain the journey of coffee, exchange, FOB, and seals in overview form at Coffee market: trade, seals, transparency.
What are our plans?
For a long time, it was a running joke among us to ask each other: "Come on, let's talk about growth again. How do we think about it?" We're a company in steward ownership, we own ourselves, and don't have to meet goals imposed by investors. We set those ourselves, grow organically, and invest where we see opportunities for development. We have no growth pressure – we have growth desire. Because when we grow, our partners grow with us. If we sell more Amigo with coffee from Yulma, Yulma can supply us more, and we become economically more important to each other.
That strengthens a connection that leads to more retention on both sides. The limit is mutual dependence, which we must avoid. We put this growing together at the center of our first Producers Conference in late June 2026. It's called in essence Creciendo Juntos – growing together. Our plans include growth, but not just in numbers, but also on an interpersonal level. We prefer to work longer-term with the same producers rather than roast more volume at all costs. We'd rather learn more from each other than make promises that are too large. Strong growth also requires that we can support it – that the team handles it and the infrastructure allows more volume. We're developing these scenarios at our own pace so that we remain reliable partners on one hand and a specialty roastery with high quality standards on the other.
In short
The coffee market has experienced extremes over the past 18 months – from an all-time high of over 442 US cents to nearly halving to around 250 US cents. What carries through all the fluctuations are relationships: order early, talk openly about prices, diversify, and stay close to people. This report is like a relationship in transition and will continue to evolve. If you have input or wishes for the next edition, please write to us at roesterei@kaffeemacher.ch.
Responsible for content: Philipp Schallberger, Kaffeemacher AG, Güterstrasse 140, 4053 Basel. Published in June 2026.